Market Insights
What Is Paper Gold and Why It’s Riskier Than You Think
Oct
When most people hear the phrase “investing in gold,” they picture a shiny coin or a heavy bar sitting in a vault. But a large portion of gold investment today never involves physical metal at all. Instead, millions of investors hold what the industry calls paper gold — financial instruments that track the price of gold without delivering actual metal. Understanding the difference between paper gold and physical gold is one of the most important steps any new precious metals investor can take. The risks involved may surprise you.
What Exactly Is Paper Gold?
Paper gold is a broad term for any financial product that gives you exposure to gold prices without giving you ownership of physical metal. The most common forms include gold exchange-traded funds (ETFs), gold futures contracts, gold certificates, and shares in gold mining companies. Each of these instruments behaves differently, but they share one key trait: you do not hold the metal itself.
A gold ETF, for example, is a fund that is supposed to be backed by physical gold held in a vault on behalf of shareholders. When you buy shares of a gold ETF through a brokerage account, you own a slice of that fund — not a specific bar or coin. Gold futures, on the other hand, are contracts to buy or sell gold at a set price on a future date. Most futures traders never intend to take delivery of the metal. They are simply speculating on price movement.
Gold certificates are another variation. These are documents issued by a bank or dealer claiming that a certain amount of gold is held on your behalf. Again, you receive paper, not metal. Each of these products trades on financial exchanges and can be bought and sold quickly, which is part of their appeal.
The Counterparty Risk Problem
The single biggest risk in paper gold is counterparty risk — the risk that the institution on the other side of your investment fails to deliver on its promise. When you own a physical gold coin, no one needs to do anything for your asset to hold value. When you own a gold ETF or certificate, your investment depends entirely on the fund manager, custodian, and banking institution all doing their jobs correctly.
During financial crises, this distinction becomes critical. If a bank that holds gold on your behalf goes bankrupt, you become a creditor of that institution. That means you stand in line with all the other creditors waiting for your share of whatever assets remain. History has shown that creditors often receive far less than the full value of what they are owed.
Gold futures carry additional layers of complexity. These contracts are leveraged instruments, meaning you can control a large amount of gold with a relatively small deposit. Leverage magnifies both gains and losses, and if prices move against you, you can face a margin call requiring you to deposit more money immediately or lose your position entirely.
The Leverage and Rehypothecation Issue
One of the less-discussed risks of paper gold involves a practice called rehypothecation. In the world of financial institutions, the same underlying asset can sometimes be pledged as collateral for multiple obligations. Critics of the gold market have long argued that the amount of paper gold outstanding — meaning all the claims on gold through ETFs, futures, and certificates — far exceeds the amount of physical gold actually available to back those claims.
If this is true at any meaningful scale, it means that in a scenario where large numbers of paper gold holders simultaneously demanded delivery of physical metal, the system could not fulfill those requests. Some estimates suggest there is far more paper gold circulating in financial markets than there is physical gold to redeem it. While the exact numbers are debated, the structural risk is real and well-documented in financial literature.
This risk does not exist with physical gold. A coin or bar in your possession is not someone else’s liability. It does not depend on any institution’s solvency, management competence, or accounting practices.
ETF Fine Print Most Investors Never Read
Gold ETFs are marketed as convenient and low-cost ways to gain gold exposure, and for certain investment strategies they serve a purpose. But the fine print in many ETF prospectuses contains language that should give any serious investor pause. Some ETFs explicitly state that shareholders have no right to demand physical delivery of gold. Others allow the fund to hold unallocated gold, meaning the fund’s gold is pooled and not assigned to specific bars traceable to specific owners.
There can also be sub-custodian arrangements, where the gold is not held directly by the fund’s named custodian but is passed down through a chain of storage relationships. Each link in that chain is another point of potential failure. Reading these documents carefully reveals that the connection between your ETF share and a real, tangible gold bar is far less direct than most investors assume.
This does not mean all gold ETFs are fraudulent — most are operated legitimately and have functioned as advertised during normal market conditions. The concern is what happens in abnormal market conditions, which is precisely when investors most need their gold holdings to perform reliably.
When Physical Gold Outperforms Paper Gold
Physical gold has historically served as a store of value through wars, currency crises, banking collapses, and periods of extreme inflation. In each of those scenarios, people who held the metal in their hands were able to use it, trade it, or preserve their wealth. People who held paper claims on gold were sometimes left with worthless documents.
Physical gold also carries no management fees, no counterparty exposure, and no dependency on electronic systems or financial infrastructure. It is as private as you choose to make it. Coins and bars can be stored at home, in a private vault, or through a third-party storage service — all options that keep the asset firmly in your control.
For investors who value genuine security and true ownership, physical metal offers something paper gold simply cannot replicate: the certainty that what you own is real and accessible regardless of what happens in financial markets.
How to Start Buying Physical Gold
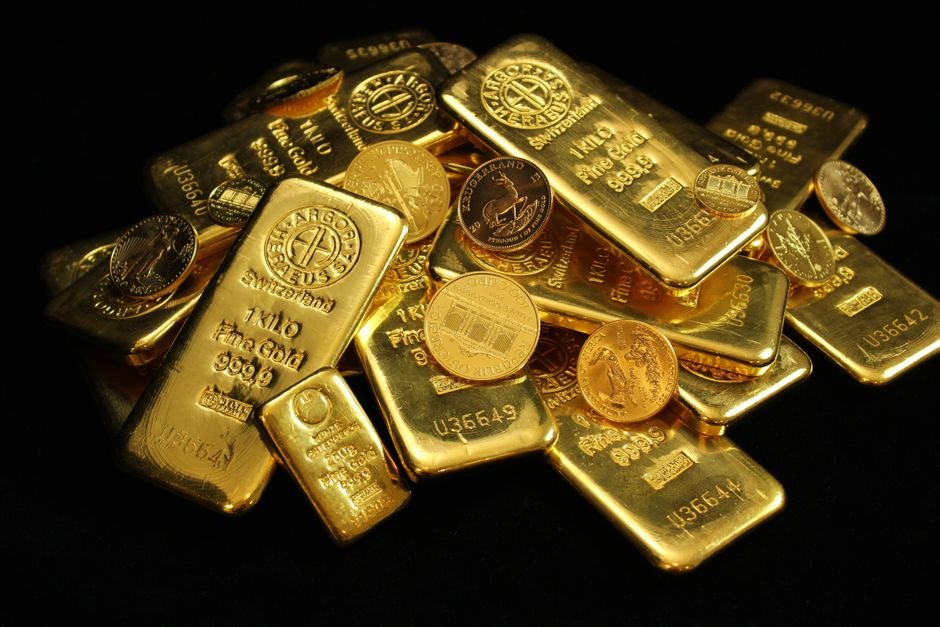
Getting started with physical gold is simpler than many new investors expect. Common entry points include gold coins minted by sovereign governments — such as American Gold Eagles, Canadian Maple Leafs, and South African Krugerrands — as well as gold bars in various sizes from one gram up to one kilogram and beyond. Coins often carry slightly higher premiums over spot price due to their collectability and liquidity, while bars typically offer lower premiums for larger purchases.
Buying from a reputable dealer is essential. Look for dealers who are transparent about pricing, clearly disclose premiums over spot, and offer secure shipping or local pickup. Absolute Bullion is a California-based precious metals dealer that offers a straightforward buying experience with live pricing available directly on the site. Checking current spot price at absolutebullion.com before you buy helps you understand what you are paying above the raw metal value.
Paper gold has a place in some financial strategies, but it is not a substitute for physical metal when security and true ownership matter most. Before you assume your gold investment is protected simply because it tracks the gold price, take a closer look at what you actually own. The difference between a paper claim and a real bar in your hand could matter enormously at exactly the moment you need your investment to hold firm. Do your research, read the fine print, and consider making physical gold part of a strategy built on real assets.
