Market Insights
Gold vs Bonds During Economic Uncertainty: Which Is the Better Safe Haven?
Sep
When economic storm clouds gather, investors instinctively reach for safe havens — assets designed to hold value when everything else is falling apart. Two of the most commonly cited options are gold and bonds, particularly U.S. Treasury bonds. Both have long histories of protecting wealth during turbulent times, but they work in very different ways. Understanding those differences can help you make smarter decisions about where to put your money when uncertainty rises.
What Makes an Asset a “Safe Haven”?
A safe haven is any asset that tends to retain or increase its value during periods of market stress, geopolitical tension, or economic slowdown. The key word is “tends” — no asset is perfectly safe under all conditions, and both gold and bonds have had periods where they disappointed nervous investors. What matters is understanding the specific conditions under which each one performs well.
Bonds, especially U.S. Treasuries, are backed by the full faith and credit of the federal government. Gold, on the other hand, is backed by nothing except its own physical scarcity and thousands of years of human trust. That distinction turns out to be enormously important depending on the type of economic trouble you are facing.
How Bonds Behave During Economic Uncertainty
When the economy slows down or investors fear a recession, they often flood into U.S. Treasury bonds. This drives bond prices up and pushes yields down. Bonds work well in deflationary environments or during sharp market selloffs where investors simply want to park cash somewhere perceived as stable. In that narrow scenario, bonds can deliver reasonable short-term protection.
However, bonds carry a significant hidden risk: inflation. When inflation rises faster than the interest rate a bond pays, the real purchasing power of your money declines. You may get your principal back at maturity, but that money buys less than it did when you invested it. The period following the COVID-19 pandemic was a painful reminder of this — bond holders watched inflation erode the real value of their fixed-income holdings even as interest rates remained historically low for an extended period.
There is also interest rate risk to consider. When the Federal Reserve raises interest rates to fight inflation, existing bond prices fall. Long-term bond holders can see significant paper losses during rate-hiking cycles, which is hardly the safe haven behavior most people expect from a defensive asset.
How Gold Behaves During Economic Uncertainty
Gold has a fundamentally different relationship with economic uncertainty. Rather than functioning like a loan to a government, gold is a hard, finite physical asset with no counterparty risk. No government can print more of it, and no central bank policy can dilute its supply overnight. These qualities make gold particularly powerful during inflationary periods, currency crises, and prolonged economic instability.
Historically, gold has demonstrated strong performance during periods of high inflation, dollar weakness, and geopolitical turmoil. It does not pay interest or dividends, which is often cited as a drawback. But during times when real interest rates — the interest rate minus inflation — are low or negative, the opportunity cost of holding gold shrinks dramatically, making it more attractive relative to yield-bearing assets.
Gold also tends to hold value across very long time horizons in a way that paper-based assets cannot always match. Civilizations rise and fall, currencies come and go, but gold has maintained its role as a store of value for thousands of years. For investors worried about systemic financial risk or a loss of confidence in fiat currency, that track record is difficult to ignore.
The Core Difference: What Kind of Risk Are You Hedging?
The most useful way to think about gold versus bonds is to ask yourself what specific risk you are trying to protect against. Bonds offer protection primarily against deflation and short-term market volatility. If you believe an economic downturn will be brief and prices will remain stable or fall, short-term Treasury bonds can serve as a reasonable holding spot.
Gold offers protection against a broader and arguably more dangerous set of risks: sustained inflation, currency devaluation, banking system stress, sovereign debt concerns, and long-term erosion of purchasing power. These are the risks that can permanently impair wealth rather than temporarily reduce portfolio value on a spreadsheet.
Many financial professionals suggest that the real question is not gold versus bonds, but rather how much of each fits your situation. A portfolio that holds some physical gold alongside other assets is not abandoning safety — it is diversifying the type of protection you have in place.
Practical Considerations for Buying Physical Gold
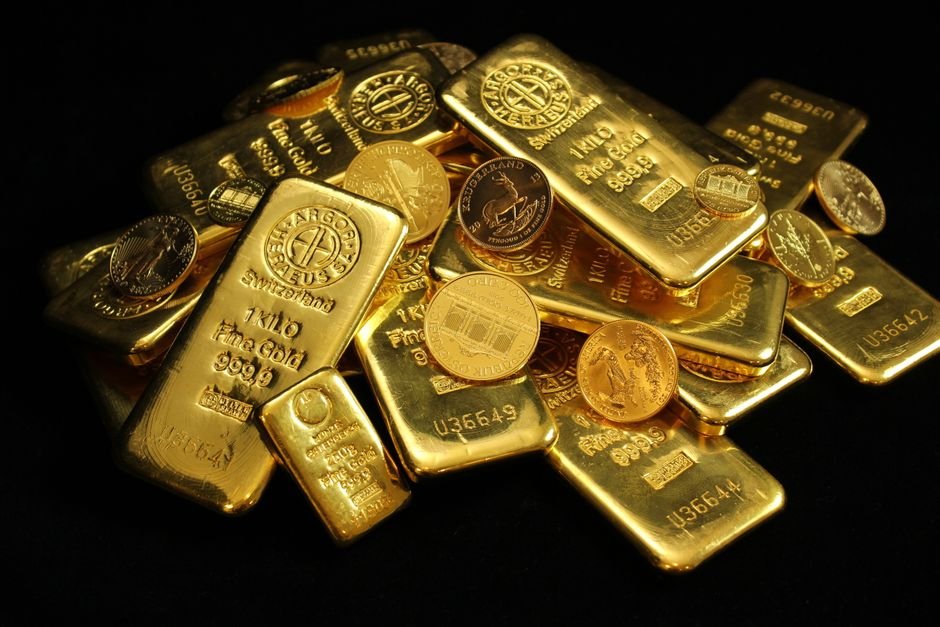
If you decide that gold deserves a place in your financial strategy, the next step is understanding your options. Physical gold — coins and bars — offers the most direct form of ownership. There are no middlemen, no fund managers, and no counterparty whose failure could affect your holding. You own the metal outright.
When buying physical gold, keep these practical points in mind:
- Buy from a reputable dealer. Work with an established, transparent precious metals dealer who clearly discloses premiums above spot price.
- Understand the premium. Physical gold always sells at a small premium above the raw spot price to cover manufacturing, distribution, and dealer costs. This is normal and expected.
- Consider storage early. Plan where you will safely store gold before you buy it. Options include home safes and professional vault services.
- Start with recognized products. American Gold Eagles, American Gold Buffalos, and standard gold bars from accredited refiners are widely recognized and easy to resell.
- Think long term. Physical gold rewards patient holders. It is not a short-term trading instrument for most individual investors.
At Absolute Bullion, you can browse a full selection of gold coins and bars at current spot price, with transparent pricing and no hidden fees. Comparing your options before purchasing is always a smart move.
Can You Hold Both Gold and Bonds?
Absolutely. Many seasoned investors hold both assets precisely because they hedge different risks. Bonds can cushion a portfolio during a deflationary recession. Gold can protect purchasing power during inflationary or currency-driven crises. Together, they can cover more ground than either one alone.
The right balance depends on your time horizon, risk tolerance, and your own read on the economic environment ahead. If you are concerned primarily about inflation, government debt levels, or geopolitical instability, tilting toward gold makes sense. If your primary concern is a short, sharp recession with stable prices, bonds may carry more of the load in the near term.
Both gold and bonds have earned their place in conversations about financial protection, but they are not interchangeable. Bonds are a promise. Gold is a possession. In an era of rising debt, persistent inflation risk, and geopolitical unpredictability, understanding that distinction could make a meaningful difference in how well your wealth holds up. Visit absolutebullion.com today to explore your gold options and take a concrete step toward building a more resilient financial foundation.
