Market Insights
IRS Rules for Gold IRA Investments: What Every Investor Must Know
Oct
Adding physical gold to a retirement account sounds straightforward, but the IRS has very specific rules that govern exactly how it works. Get the details right and a Gold IRA can be a powerful way to diversify your retirement savings. Get them wrong and you could face penalties, taxes, and a disqualified account. Whether you are just starting to explore the idea or are ready to open an account, understanding the regulatory framework is the most important first step you can take.
What Is a Gold IRA and How Does It Differ from a Regular IRA?
A Gold IRA is a self-directed individual retirement account that holds physical precious metals instead of — or in addition to — conventional assets like stocks and bonds. The “self-directed” part is critical. A standard IRA managed by a brokerage limits you to securities that the custodian offers. A self-directed IRA gives you the legal authority to hold alternative assets, including IRS-approved physical gold, silver, platinum, and palladium.
Despite the added flexibility, a Gold IRA operates under the same basic IRS rules as any other IRA. Contribution limits, rollover rules, required minimum distributions, and tax treatment all follow the same framework. The key differences involve which metals qualify, where those metals must be stored, and how transactions must be structured. Ignoring any of these distinctions is where investors most often run into trouble.
Which Gold Products Does the IRS Actually Allow?
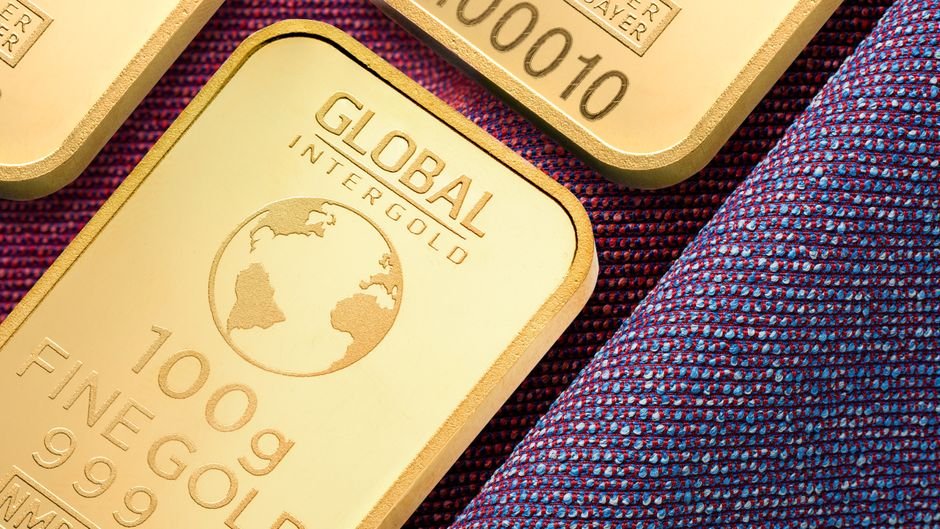
Not every gold coin or bar you can buy qualifies for an IRA. The IRS requires that gold held inside a retirement account meet a minimum fineness standard of .995 purity. There are a small number of exceptions, but the purity threshold eliminates many popular collector and numismatic coins from consideration entirely.
Products that generally meet IRS requirements include the American Gold Eagle coin — which is the notable exception to the .995 rule because it is explicitly authorized by statute — American Gold Buffalo coins, Canadian Gold Maple Leaf coins, and gold bars and rounds produced by an approved refinery or assayer. Rare or collectible coins, jewelry, and any gold product that does not meet the purity standard are prohibited. Before you purchase, confirm that the specific product you are buying is IRA-eligible. Reputable dealers like Absolute Bullion can help you identify which products qualify.
The Custodian Requirement You Cannot Skip
One of the most important IRS rules is that you cannot personally hold the gold inside your IRA. The IRS requires that all assets in a self-directed IRA be held by a qualified trustee or custodian — typically a bank, credit union, or IRS-approved non-bank custodian. You must open your Gold IRA through one of these entities, not simply buy gold and store it yourself while calling it a retirement account.
Attempting to take personal possession of IRA gold — sometimes marketed as a “home storage IRA” — is widely considered a distribution by the IRS. That means the full value of the metals could become immediately taxable, and if you are under 59½, you would also owe a 10% early withdrawal penalty. The home storage IRA concept has been successfully challenged in federal tax court, so it is a risk not worth taking. Always work with a legitimate custodian who specializes in self-directed accounts.
Storage Rules: Approved Depositories Only
Closely related to the custodian requirement is the storage requirement. IRS rules mandate that the physical gold in your IRA be stored at an approved depository — a secure, insured facility that meets the IRS’s standards. Your custodian will typically work with one or more depositories and will handle the logistics of transferring your metals there after purchase.
When choosing a depository, you will generally encounter two types of storage: segregated and commingled. Segregated storage means your metals are stored separately from other clients’ holdings and are specifically identified as yours. Commingled storage places your metals alongside other clients’ holdings of the same type. Segregated storage usually costs more but offers an extra layer of accountability. Ask your custodian to explain both options clearly before you decide.
Rollovers, Transfers, and Contribution Rules
You can fund a Gold IRA in three main ways: a direct contribution, a rollover from an existing retirement account, or a trustee-to-trustee transfer. Each method comes with its own rules. Annual contribution limits for Gold IRAs are the same as traditional and Roth IRAs — limits the IRS adjusts periodically — so check the current limits on IRS.gov before contributing.
A rollover allows you to move funds from a 401(k), 403(b), or another IRA into your Gold IRA. If you receive the funds directly, the IRS gives you 60 days to deposit them into the new account. Miss that window and the distribution becomes taxable. A trustee-to-trustee transfer, where funds move directly between custodians without passing through your hands, is generally cleaner and avoids the 60-day clock entirely. Most investors prefer the transfer method for that reason. Also note that you are limited to one IRA-to-IRA rollover per 12-month period under IRS rules.
Distributions, RMDs, and Tax Treatment
A Gold IRA is subject to the same distribution rules as a conventional IRA. Withdrawals before age 59½ are generally subject to ordinary income tax plus a 10% early withdrawal penalty unless a specific exception applies. After 59½, distributions are taxed as ordinary income for a traditional Gold IRA. A Roth Gold IRA, funded with after-tax dollars, allows for tax-free qualified distributions.
Required Minimum Distributions — commonly called RMDs — apply to traditional Gold IRAs starting at the age specified under current IRS rules. This is where physical gold adds a practical complication. Unlike cash, gold cannot simply be electronically transferred. To satisfy an RMD, you must either liquidate a portion of your metals for cash or take an in-kind distribution of the physical gold, which is then valued at the spot price on the distribution date and taxed accordingly. Planning for RMDs ahead of time helps avoid a forced sale at an inopportune moment.
Conclusion
A Gold IRA can be a meaningful part of a long-term retirement strategy, but only when it is set up and maintained according to IRS rules. The requirements around metal purity, custodians, approved storage, and distribution rules are non-negotiable — and the penalties for getting them wrong are significant. Take the time to understand each rule before you commit. If you are ready to explore IRA-eligible gold and silver products, visit absolutebullion.com to browse current inventory at spot price and speak with a team that can point you toward the right products for your goals.
