Market Insights
How Gold Preserves Generational Wealth: A Timeless Strategy for Families
Oct
Every generation faces the same fundamental challenge: how do you protect what you’ve built and pass it on to the people you love? Stocks can crash, currencies can inflate, and real estate markets can stagnate. But gold has outlasted empires, survived financial crises, and maintained purchasing power across centuries. For families thinking beyond the next quarter — thinking in decades — gold offers something rare in the modern financial world: genuine staying power. Understanding how gold functions as a generational wealth tool can help you make smarter decisions for your family’s long-term future.
Why Gold Has Always Been a Store of Value
Gold’s role as a store of value isn’t a modern invention. Civilizations across every continent have independently recognized gold as a reliable measure of wealth. The reason is simple: gold is scarce, durable, and cannot be created out of thin air. Unlike paper money, no government or central bank can print more of it. That built-in scarcity is what has protected gold’s purchasing power through countless economic cycles.
Over long stretches of time, gold has historically maintained its ability to buy meaningful goods and services. An ounce of gold in ancient Rome could clothe a man well. That same ounce today still represents significant purchasing power. This isn’t true of most paper currencies, many of which have lost the vast majority of their value over decades due to inflation. For families thinking in generational terms, that kind of stability is worth serious attention.
The key distinction is that gold doesn’t “earn” a return the way a dividend stock or rental property might. What it does is preserve. It acts as a foundation — a financial anchor that holds value when other assets struggle. That makes it a powerful complement to a broader family wealth strategy rather than a replacement for other investments.
Gold as a Hedge Against Inflation and Currency Risk
Inflation quietly erodes the value of cash savings over time. A dollar today will not buy what it bought twenty years ago, and there is every reason to expect that trend to continue. Families who hold significant cash savings without any hard asset protection risk watching the real value of that wealth shrink with each passing year.
Gold has historically moved in a different direction than paper currencies during periods of significant inflation. When purchasing power falls, the price of gold in those currency terms has often risen. This inverse relationship makes gold particularly useful as a hedge — a portion of the family portfolio designed specifically to offset losses elsewhere during inflationary periods.
Currency risk is a related concern, especially for families with international ties or those who simply worry about the long-term health of the U.S. dollar. Because gold is priced globally and recognized universally, it transcends any single nation’s monetary policy. No matter what decisions are made in Washington or on Wall Street, an ounce of gold remains an ounce of gold.
Physical Gold vs. Paper Gold: What Families Should Know
When building generational wealth, the type of gold you own matters enormously. There is a meaningful difference between owning physical gold — coins and bars you can hold — and owning paper gold such as ETFs, futures contracts, or gold-backed certificates. For generational transfer purposes, physical gold has clear advantages.
Physical gold has no counterparty risk. It doesn’t depend on a brokerage firm staying solvent, a fund manager making good decisions, or a financial institution honoring its obligations. When you hold a gold coin in your hand, you own it outright. That simplicity is especially important when wealth passes from one generation to the next. There are no accounts to transfer, no passwords to recover, and no institutions standing between the asset and its new owner.
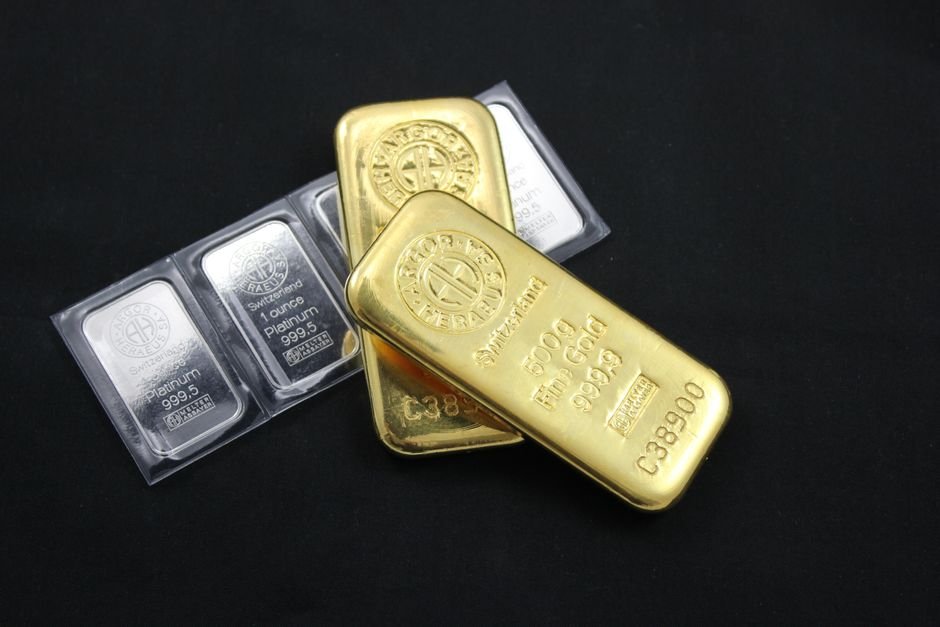
Gold coins and bars are also highly liquid. They can be sold quickly through reputable dealers at current spot price, and they are recognized worldwide. Popular choices for family wealth building include American Gold Eagles, Canadian Gold Maple Leafs, and gold bars from accredited refineries. Each offers a combination of recognized purity, easy valuation, and straightforward resale.
How to Start Building Gold Wealth for Your Family
Getting started doesn’t require a large upfront commitment. Many families begin by purchasing one or two coins and adding to their holdings gradually over time. This approach — sometimes called dollar-cost averaging — means you buy at a variety of price points rather than committing all your resources at once. It reduces timing risk and makes gold ownership accessible even on a modest budget.
Here are some practical steps to begin:
- Define your purpose. Are you building an emergency reserve, protecting against inflation, or leaving a legacy? Your goal shapes how much you buy and what form you buy it in.
- Start with recognized coins or bars. Government-minted coins like American Gold Eagles are easy to value, easy to sell, and widely trusted.
- Buy from a reputable dealer. Work with an established dealer who is transparent about pricing and product authenticity. Absolute Bullion offers a clear, straightforward buying experience for families at every stage of their precious metals journey.
- Store it securely. Consider a home safe for smaller holdings and a professional vault or bank safe deposit box for larger amounts.
- Document your holdings. Keep clear records of what you own, where it is stored, and how you want it passed on. This is essential for smooth generational transfer.
Passing Gold to the Next Generation
One of gold’s most underappreciated advantages is how cleanly it transfers between generations. A gold coin requires no brokerage account, no financial institution, and no complex legal maneuvering to change hands. You can include physical gold in a will, place it in a trust, or gift it directly during your lifetime. Each approach has different tax implications, so consulting an estate planning attorney is always a smart move.
Beyond the legal mechanics, gold also carries something intangible: meaning. Handing a grandchild a gold coin that has been in the family for thirty years is a lesson in patience, discipline, and long-term thinking that no financial lecture can match. It makes the concept of wealth preservation real and personal in a way that a brokerage statement never will.
Families who make gold part of their ongoing financial conversations — explaining why it’s held, what it represents, and how to manage it responsibly — tend to pass on not just an asset but a mindset. That financial wisdom is itself a form of generational wealth.
How Much Gold Should a Family Hold?
There is no universal answer, and anyone who tells you otherwise is oversimplifying. Many financial advisors suggest that hard assets like gold represent somewhere between five and fifteen percent of an overall portfolio, but that range depends heavily on your family’s specific circumstances, risk tolerance, and goals. The right amount is the amount that makes sense for your situation after careful thought and, ideally, professional guidance.
What matters more than a specific percentage is consistency and intention. Families who hold gold as a deliberate part of a long-term strategy — rather than as a reactive panic purchase — tend to get the most out of it. Regular, planned additions are more effective than sporadic large buys driven by market fear.
Building generational wealth is one of the most meaningful financial goals a family can pursue, and gold has earned its place in that strategy through thousands of years of proven performance. If you’re ready to take the first step, visit absolutebullion.com to explore current offerings at spot price and speak with a team that understands what long-term wealth preservation really means.
